- Surging AI Demand Driving Flame Retardant Requirements
- Thermal Management Challenges from High Power Consumption
– NVIDIA GB200 and AMD MI350 AI chips exceed 1,200W, causing server cabinet hotspots >150°C.
– Traditional PVC housings risk deformation/ignition, requiring UL94 V-0 certification (self-extinguishing within 2 seconds).
– 2025 global AI server shipments: 2.4M units (41.5% YoY), with PVC housings >60% share, boosting demand for heat-resistant retardants by 300%.
- Material Performance Upgrades
– Heat Resistance: Retardants must ensure structural stability at 180°C (traditional limit: 140°C), e.g., Wanhua’s castor oil-based WSFR-2025 series.
– Low Dielectric Loss: 5G/6G transmission requires Dk <2.8 and Df <0.002 (critical for Huawei Ascend 910B certification).
—
- Core Applications Accelerating Technological Innovation
- Servers & Data Centers
– Liquid Cooling Pipes: PVC coolant pipes use red phosphorus-lignin nanocomposites (Suzhou Suli tech), reducing smoke density 50% while resisting corrosion.
– Server Housings: Phosphorus-nitrogen (P-N) systems replace bromine-antimony, cutting costs 15% and eliminating halogens (EU plans €500/ton tax on brominated retardants by 2026).
- Consumer Electronics
– AI PCs/Laptops: Higher heat dissipation increases retardant loading by 30–50%. 2025 AI laptop upgrades will drive CCL flame retardant demand up 150%.
– Chip Substrates: Copper-clad laminates (CCL) require 260°C reflow tolerance. Wanhua’s antimony-free P-N systems comply with EU RoHS (Sb limit: 800ppm).
—
III. Supply Chain Shifts and Strategic Responses
- Raw Material Substitution
– China’s antimony export controls pushed prices to $52,000/ton (Q1 2025), raising bromine-antimony costs 47%. Bio-based alternatives (e.g., castor oil derivatives) gain traction.
– GEM’s supercritical CO₂ recycling achieves 92% antimony recovery; 10,000-ton/year line operational in 2026.
- Corporate Strategies
– Wanhua Chemical: Added 5,000-ton P-N retardant capacity (Nantong, April 2025), supplying Huawei Cloud data centers.
– Clariant: Partners with CATL on flame-retardant PVC coatings for liquid cooling, enhancing thermal conductivity 40%.
—
- Future Trends: Sustainability and Intelligence
- Halogen-Free Dominance
– EU policies to boost P-N retardant market share from 35% (2025) to 60% (2030).
- Multifunctional Integration
– AI-driven formulation systems (e.g., Wanhua’s “FlameCloud”) cut R&D time 30%, integrating flame retardancy, thermal conduction, and anti-static properties.
- Regionalized Production
– Southeast Asia emerges as low-cost hub. Suzhou Suli’s Philippine plant (2026) to supply Tesla’s Mexico AI server base.
—
Conclusion
> AI computing is transforming flame retardants from passive fire protection to active thermal management, with innovations focusing on:
> ① Extreme Heat Resistance
> ② Ultra-Low Dielectric Loss
> ③ Halogen-Free Formulations
>
> 2025 demand for AI server flame retardants will hit 23,000 tons (300% YoY). Industry leaders must build competitive advantages through:
> • Bio-based substitutes
> • Closed-loop recycling
> • AI-accelerated R&D
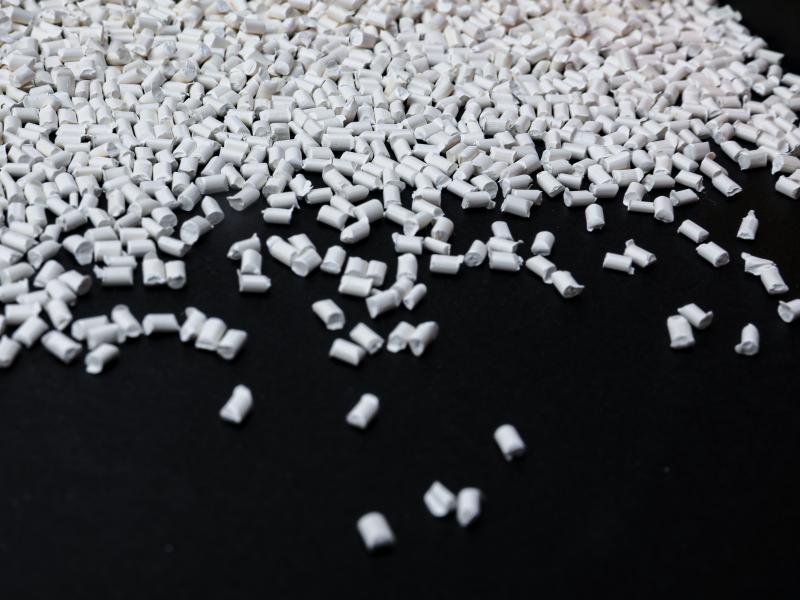
Companies mastering P-N synergistic patents (e.g., Wanhua WSFR-2025) and liquid cooling compatibility (e.g., Suzhou Suli’s red phosphorus masterbatch) will dominate the AI-driven flame retardant market.